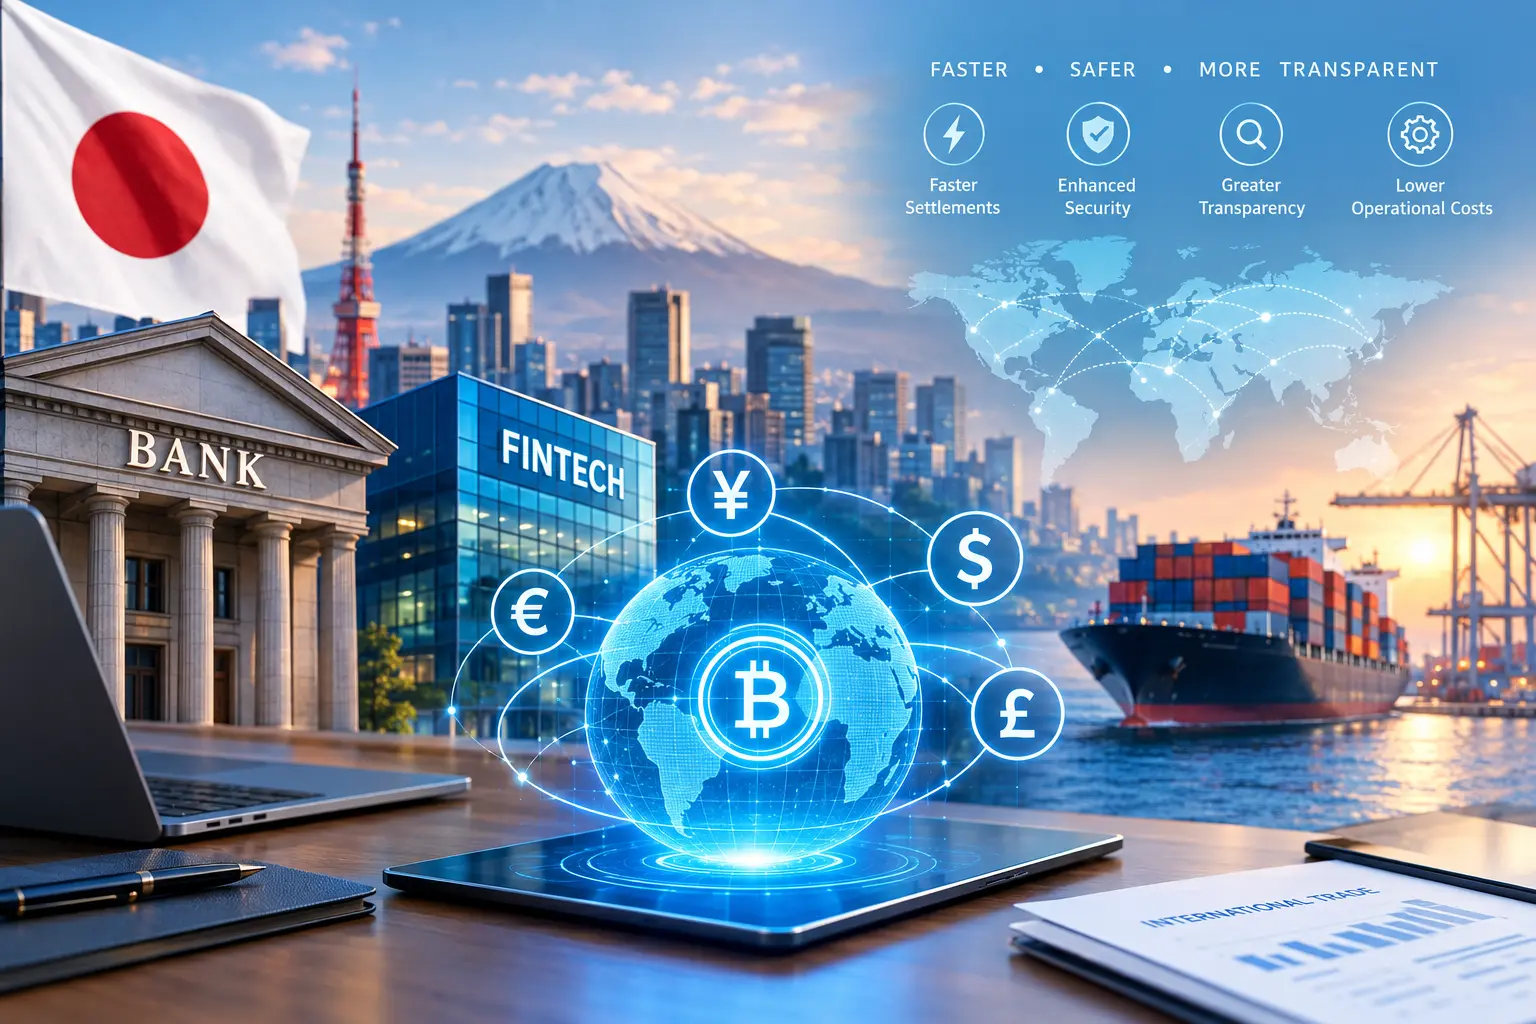
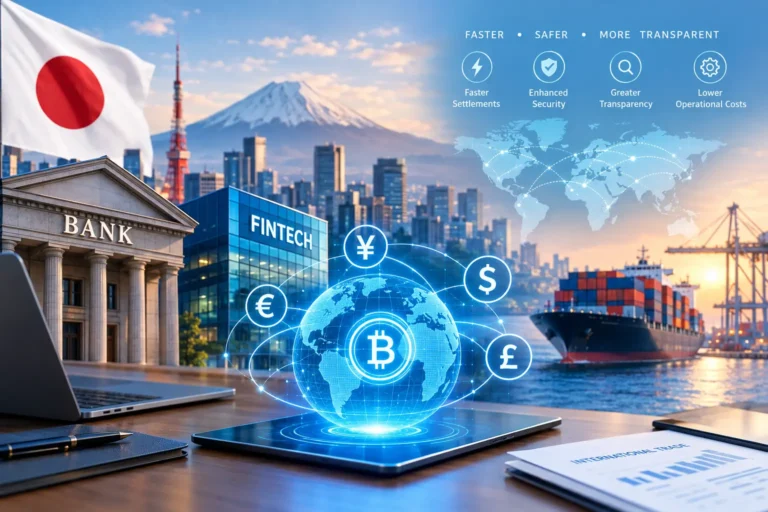
Japan is strengthening its position in digital finance as banks and fintech companies explore new ways to simplify international trade payments. Traditional cross border transactions often involve several financial institutions, lengthy processing times, and high administrative costs. Digital currency solutions offer an opportunity to address these challenges while improving transparency and operational efficiency.
As businesses expand internationally, reliable payment infrastructure becomes increasingly important. Consequently, financial institutions are exploring digital settlement systems that could help companies transfer funds more quickly and manage international transactions with greater confidence. These developments also represent important finance industry updates for organizations seeking modern alternatives to conventional banking processes.
Why Digital Currency Matters for Trade Settlements
International trade depends on timely payments between importers, exporters, suppliers, and financial intermediaries. However, differences in banking systems, operating hours, compliance requirements, and currency conversion procedures can delay settlements.
Digital currency infrastructure could reduce some of these inefficiencies by enabling transactions through connected digital platforms. Depending on the system, payments may be processed with fewer intermediaries and improved visibility into transaction status. Moreover, automated settlement mechanisms can help reduce reconciliation work and support more accurate financial records.
For Japanese businesses, these capabilities could improve working capital management. When payments arrive sooner, companies may gain greater flexibility in managing supplier obligations, inventory purchases, and cash flow forecasts. Therefore, digital settlement technology is becoming an important area of technology insights for finance leaders.
Japanese banks bring established customer relationships, regulatory expertise, and experience managing large financial transactions. Meanwhile, fintech companies contribute software development capabilities, digital payment platforms, and innovative approaches to transaction processing.
Their collaboration could help connect established banking infrastructure with emerging digital financial networks. Rather than replacing traditional banking overnight, these partnerships may introduce digital settlement capabilities alongside existing payment services.
Furthermore, financial institutions are exploring different approaches to digital money, including tokenized deposits, regulated stablecoins, and central bank digital currency initiatives. These instruments have distinct legal structures, risk profiles, and settlement characteristics. Their practical applications depend on the technology, regulatory framework, and participating institutions.
For CFOs, understanding these differences is essential. The latest IT industry news increasingly highlights how financial technology can influence treasury operations, transaction security, and international business relationships.
Benefits for Corporate Treasury and Cash Flow
Digital settlement systems could offer meaningful advantages for corporate treasury teams. Faster payment processing may help businesses monitor incoming and outgoing funds more accurately. In addition, improved transaction visibility could support better cash flow forecasting and reduce uncertainty around payment completion.
For companies operating across several markets, these improvements may simplify the management of multiple banking relationships. Treasury departments could potentially spend less time investigating delayed payments and reconciling inconsistent transaction records.
At the same time, finance leaders should evaluate whether the benefits justify the implementation costs. Integration with enterprise resource planning systems, accounting software, and existing banking platforms may require investment. Nevertheless, a carefully planned rollout could create long term operational value.
Finance teams should also monitor how digital payment developments influence commercial relationships. Faster and more predictable settlements may strengthen supplier confidence, support procurement decisions, and create opportunities for more effective sales strategies and research into international markets.
Regulatory Compliance and Cybersecurity Challenges
Despite their potential, digital currency settlements introduce important risks. Financial institutions must address anti money laundering requirements, customer verification, sanctions screening, transaction monitoring, and applicable data protection rules.
Cybersecurity is equally important. Digital platforms may face unauthorized access, software vulnerabilities, operational disruptions, and fraud attempts. Consequently, banks and fintech providers need robust security controls, clear accountability, and reliable recovery procedures.
Regulatory clarity also remains essential because different digital instruments may be subject to different legal requirements. Companies should confirm how settlement arrangements affect accounting treatment, tax reporting, foreign exchange exposure, and contractual obligations.
In addition, employees need appropriate training to manage new systems effectively. HR trends and insights can help organizations understand the importance of developing digital finance skills, while marketing trends analysis can help financial service providers communicate new offerings responsibly and build customer trust.
What CFOs Should Consider Before Adopting Digital Settlements
CFOs should begin by identifying payment processes that create the greatest delays or administrative costs. International supplier payments, recurring cross border transactions, and complex reconciliation procedures may provide useful starting points for evaluating potential improvements.
Next, finance teams should compare available settlement models and assess their compatibility with existing banking partners. It is important to understand transaction fees, liquidity requirements, currency conversion costs, settlement finality, and the legal protections available if a transaction fails.
Pilot projects can provide practical evidence before a wider rollout. By measuring processing times, reconciliation accuracy, operational expenses, and compliance performance, businesses can determine whether a new system delivers measurable value.
Moreover, finance leaders should work closely with technology, compliance, procurement, and human resources teams. This collaborative approach helps organizations balance innovation with risk management and employee readiness.
Practical Insights for Finance Leaders
Japan’s digital currency developments demonstrate how payment innovation could reshape international commerce. However, successful adoption requires more than new technology. Businesses need clear financial objectives, dependable partners, strong governance, and measurable performance indicators.
CFOs should follow finance industry updates and relevant regulatory announcements to understand how digital settlement options evolve. They should also assess whether emerging solutions can improve liquidity, reduce transaction friction, and support international growth without introducing unacceptable risks.
As these systems mature, organizations that combine careful financial planning with informed technology decisions may be better positioned to respond to changing trade requirements.
Reach out to CFOInfoPro to explore practical financial strategies that help your organization make informed decisions and prepare for the future of digital finance.
Source – nikkei