Moving to France involves more than finding accommodation and settling into a new routine. Managing everyday finances is equally important, particularly for people receiving salaries, paying rent, transferring money internationally or handling household expenses. For this reason, knowing how expats can manage banking in France in 2026 can make the transition considerably easier.
The French banking system includes traditional banks, online banking providers and payment institutions. Consequently, newcomers have several options depending on their residency status, financial requirements and preferred way of managing money.
Before choosing an account, expats should consider transaction costs, digital services, international transfers, payment facilities and access to customer support.
Opening a French Bank Account
Opening a bank account is often one of the first financial tasks after moving to France. According to the Banque de France and French public administration guidance, applicants can generally be asked to provide valid identification and proof of address. Banks may also request information about income, employment, financial circumstances and the intended use of the account.
Therefore, preparing documentation before applying can make the process more straightforward. Expats should also understand that individual banks can apply their own account opening requirements within the applicable regulatory framework.
For online applications, additional identity verification procedures may apply. In some cases, a bank can request an initial transfer from another account held in the applicant’s name or additional identification information.
Choosing Between Traditional and Digital Banking
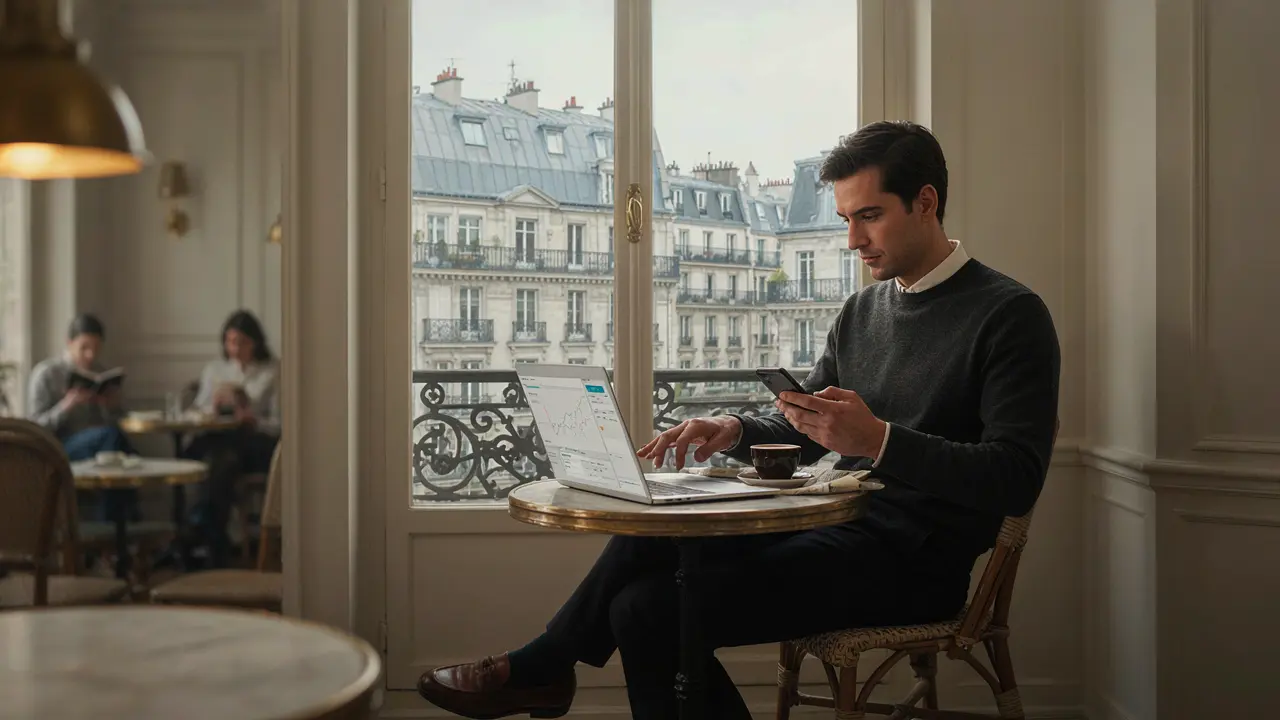
Traditional French banks can provide branch access and personal assistance, which may be useful for newcomers who are unfamiliar with local financial procedures. Meanwhile, digital banks and payment institutions can offer convenient account management through mobile applications and online platforms.
The right option depends on individual circumstances. For example, an expat who regularly sends money abroad may place greater importance on international transfer services and currency conversion costs. Conversely, someone primarily managing household expenses in France may focus on local payments, debit card facilities and account fees.
Furthermore, digital banking can complement wider Technology insights by giving customers faster access to balances, payments and transaction information.
Managing International Money Transfers
International transfers can become an important consideration for expats who continue to receive income from another country or support family members overseas. Exchange rates and transfer fees can affect the amount ultimately received, so comparing available services before sending larger amounts can help with financial planning.
In addition, expats should maintain clear records of international transactions. This can make personal budgeting easier and may be useful when preparing financial documentation or discussing cross border tax matters with a qualified professional.
Finance industry updates also demonstrate the continuing development of digital payment services and international financial technology. As a result, customers increasingly have access to faster and more transparent ways to manage cross border payments.
Understanding the Right to a Bank Account
Some expats may encounter difficulties when trying to open a French bank account. French banking rules provide a legal right to an account in certain circumstances. The Banque de France explains that people who are domiciled in France and do not have an individual bank account can use the relevant procedure after receiving a refusal from a bank. Certain French nationals living abroad and foreign nationals legally resident in another European Union country can also qualify under specified conditions.
The procedure involves submitting supporting documents and a refusal from a bank. Subsequently, the Banque de France can designate a financial institution that must provide an account with basic banking services when the legal conditions are met.
This protection can be particularly relevant for newcomers who experience difficulty accessing conventional banking services.
Keeping Banking Secure and Organised
Once an account has been established, maintaining good financial habits becomes essential. Expats should monitor transactions regularly, activate appropriate security notifications and protect online banking credentials.
Moreover, keeping personal and financial documents organised can simplify future administrative tasks. Digital statements, employment records, tax documents and evidence of international transfers should be stored securely.
These practices also align with broader IT industry news concerning cybersecurity and the growing importance of protecting financial information in digital environments.
Connecting Banking With Wider Financial Planning
Banking should form part of a broader financial plan rather than being treated as an isolated administrative task. Expats may need to consider taxation, savings, insurance, pensions, investments and currency exposure depending on their circumstances.
For example, someone working in France while retaining financial commitments in another country may need to monitor two different financial systems. Consequently, understanding residency, reporting obligations and applicable tax rules can be important before making significant financial decisions.
Professional advice may be appropriate where cross border taxation or complex investments are involved.
What Expats Should Know in 2026
Knowing how expats can manage banking in France in 2026 means looking beyond simply opening an account. The broader objective is to create a practical financial system that supports everyday spending, international transactions, savings and long term planning.
Technology is making banking increasingly accessible, while regulatory protections provide additional support for people who encounter difficulties accessing basic services. At the same time, responsible financial management remains dependent on understanding personal circumstances and keeping accurate records.
HR trends and insights can also be relevant for employees relocating to France because salary arrangements, employment benefits and workplace administration can influence banking requirements. Similarly, Sales strategies and research and Marketing trends analysis can provide broader business context for professionals working across international markets.
Insights for Smarter Expat Banking
Expats should begin by establishing their immediate banking requirements and gathering the documents likely to be requested. Comparing account costs, digital features, payment facilities and international transfer options can then help identify an appropriate solution.
Furthermore, maintaining a clear separation between everyday spending, savings and international obligations can make budgeting easier. Regularly reviewing account activity can also help identify unnecessary fees and improve financial visibility.
Ultimately, successful financial management in France depends on combining suitable banking services with careful planning. By understanding available options and keeping up with Finance industry updates, expats can create a more organised approach to managing money while adapting to life in France.
For more practical financial insights and expert perspectives, reach out to CFOInfoPro for guidance on evolving finance topics and international financial management.
Stay informed with CFOInfoProfor valuable Finance industry updates, business insights and strategies that support smarter financial decisions.
Source – expatica